“Knock for Knock Form” A Small Thing Every Insured Driver Must Know Before It Becomes a Big Problem Insurance Companies Never Tell You

When it comes to motor insurance whether it is first-class, second-class, or third-class insurance many people believe that simply “having insurance” is enough. If an accident occurs, they assume they can just call the insurance company, wait for the surveyor, and everything will be resolved smoothly.

In reality, motor insurance involves many important details that most policyholders either do not know or have never been told. One of the most crucial documents that every insured driver should always keep in their vehicle is the “Knock for Knock Form.”

This single sheet of paper can save you time, prevent disputes with the other party, and protect you from future insurance claim problems.

In this article, Attorney Arm shares real-life experience to help insured drivers understand their rights and avoid mistakes in emergency situations.

A Real Experience! When Even a Lawyer Faces a “Knock for Knock” Issue
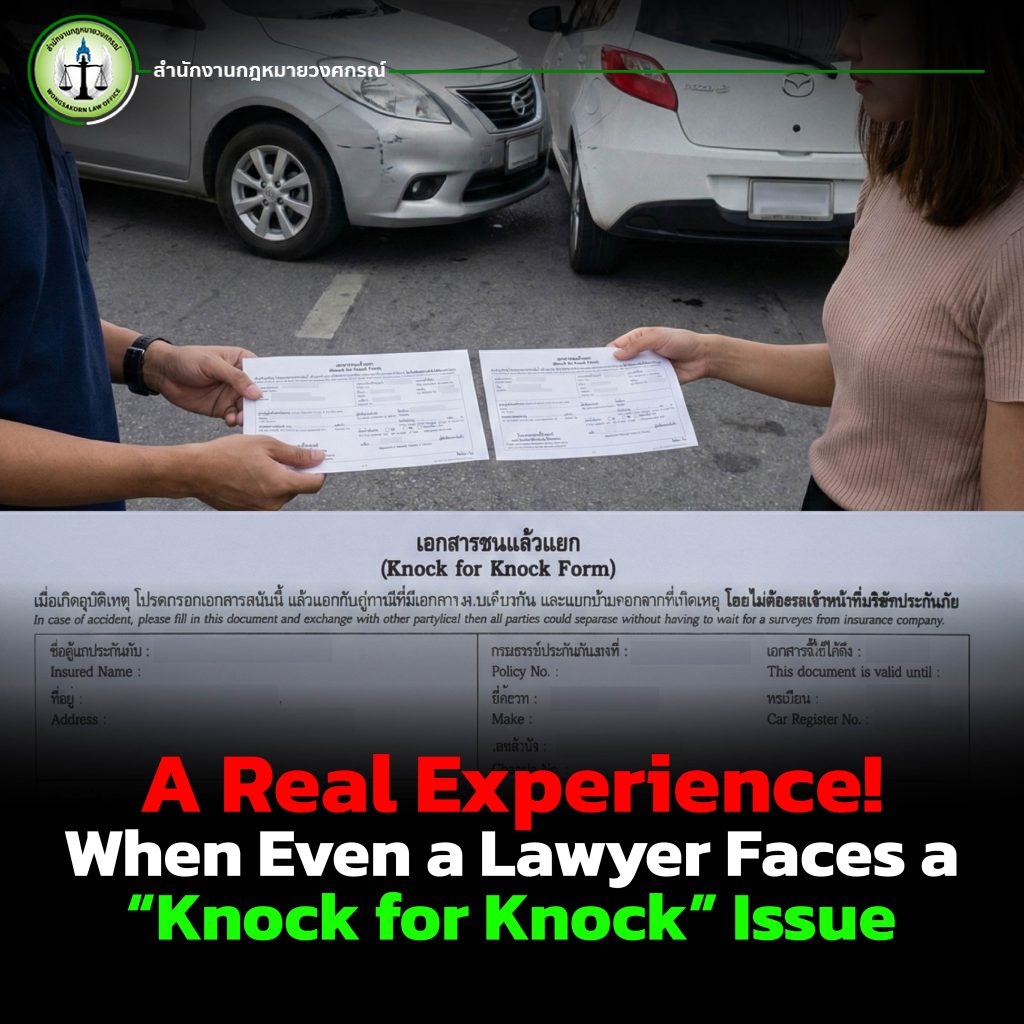
One day, Attorney Arm was involved in a rear-end collision. His vehicle was damaged, but fortunately, no one was injured and the damage was not severe.

At the time, both parties were in a hurry. Attorney Arm politely asked the other driver:

“Do you accept responsibility?”

The other party appeared confused, even though under traffic law, rear-end collisions clearly place fault on the vehicle behind. To avoid prolonging the situation, Attorney Arm then asked:

“Do you have a Knock for Knock Form?”

This form is issued by insurance companies to their policyholders. Both parties agreed to fill out and exchange the Knock for Knock Forms and then left the scene calmly, without argument or conflict.

The Problem Begins When the Other Party Calls Their Insurance Company
After leaving the scene, the other driver contacted their insurance company and told the call center that:

“The other party was in a hurry and wanted to exchange claim forms.”

Surprisingly, the insurance staff responded:

“That is not allowed. Our officer must inspect the accident scene.”

Attorney Arm then contacted the insurance company’s call center himself, politely explaining the situation and asking for the staff member’s name, but received no clear response.

He explained that the Knock for Knock Form clearly states:

“In the event of an accident, please complete this form, exchange it with the other party who has the same form, and leave the scene without waiting for an insurance officer.”

Unexpectedly, the insurance staff replied that they were “not familiar with the Knock for Knock Form,” even though it was issued by their own company.

When an Insurance Company Does Not Recognize Its Own Document
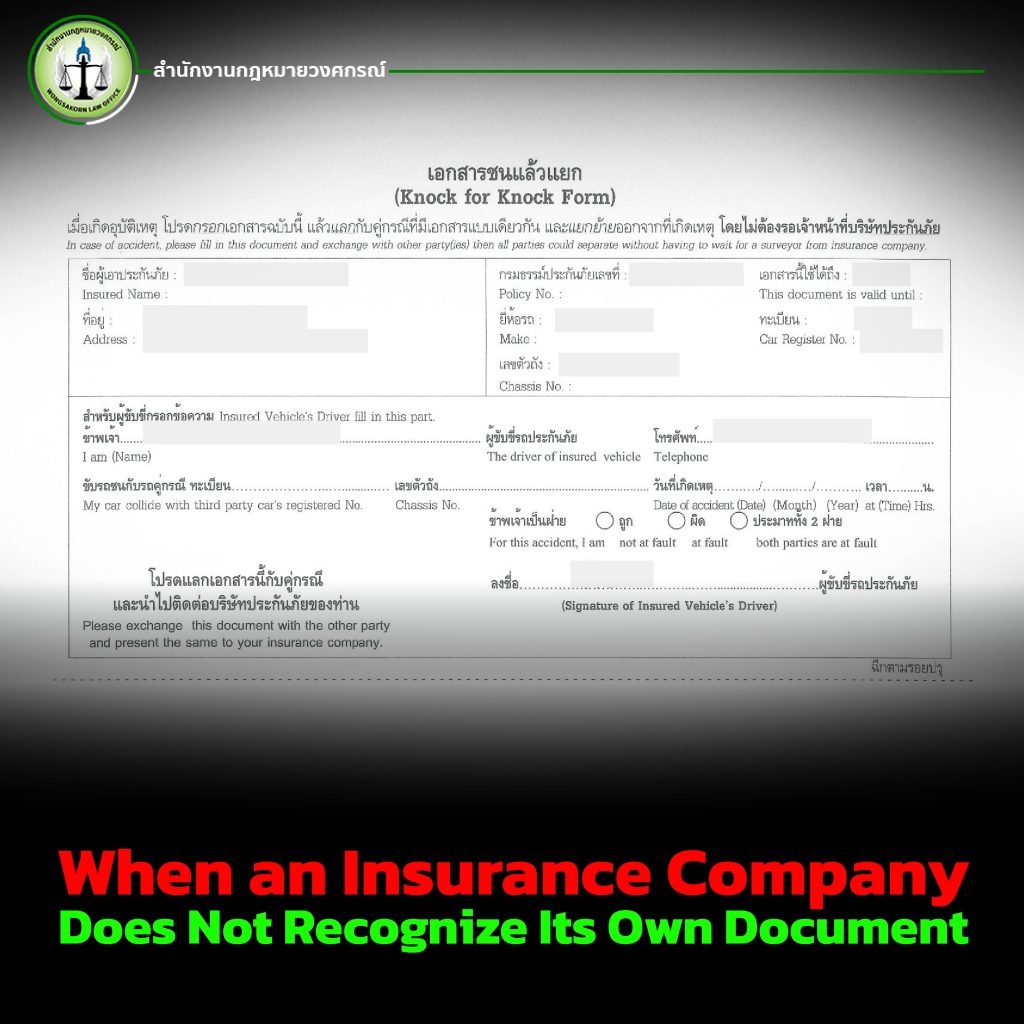
This incident left Lawyer Arm puzzled. How could an insurance company employee be unaware of a document issued by their own company?

This is a situation many policyholders may encounter but do not know how to handle. Some may simply comply with the insurance company’s instructions, believing that “they must know better.”

In fact, policyholders have the right to use the Knock for Knock Form in accordance with their insurance policy.

An Important Lesson for All Insured Drivers

This case clearly demonstrates that:

  • Even if you have insurance
  • Even if you do everything correctly
  • If you do not understand your own rights, you may still face claim denial or unnecessary delays

This is why policyholders should not rely solely on what insurance companies say, but must also understand their policy documents and rights.

What Should You Do If an Accident Occurs and You Have a Knock for Knock Form?

1.Stay calm and do not act emotionally
Accidents can happen to anyone.

2.Exit the vehicle politely and speak calmly to the other party
A friendly attitude can prevent escalation.

3.Complete and exchange the Knock for Knock Form
No need to wait for an ins insurance officer if the form allows it.

4.Take photos of the damage and accident scene
Keep evidence.

5. Keep all documents safely

What If the Insurance Company Refuses to Process the Claim?
If you encounter situations such as:

  • The insurance company refuses to pay
  • Staff claim it is “not possible” despite clear documentation
  • Liability is denied without reasonable explanation

Do not let yourself become a victim.

You may consult a lawyer immediately, especially one experienced in insurance law. Insurance companies have legal teams involved in every case, even before accidents occur.

Having Insurance Is Not Enough You Must Know Your Rights
Insurance exists to protect policyholders, not to create problems.

The Knock for Knock Form is your right. Knowing how to use it correctly can save you time, money, and stress.

If you experience problems with insurance claims, vehicle accidents, or unjust claim denials, do not hesitate to consult Wongsakorn Law Office, so you do not become a victim of the insurance system you paid for.
The Repair Shop Said “No Signature, No Repair” But the Car Still Got Fixed Because Someone Knew Their Rights!

Car owners must understand their legal rights before becoming victims of insurance companies.

In recent months, issues involving car repair shops and the insurance claim process have become unavoidable for many vehicle owners. One common situation is when a repair shop demands that the owner sign a document acknowledging that the repair will take more than 15 days and refuses to repair the car unless the owner signs. In reality, however, car owners are not required to sign any such documents unless the insurance policy explicitly includes that requirement.

Many people may not realize that the auto insurance policy they purchased does not require them to travel to the repair shop to sign a consent form regarding the repair timeframe. Buying insurance means purchasing a service from the insurance company. Once the insured pays the premium, they are entitled to convenience not extra burdens imposed afterward.

You Paid for a Service, Yet You’re Not Receiving It — Why?

There are two main reasons:

1. Repair shops want to protect themselves

If the repair takes longer than expected, they want the insured to accept it in advance so they won’t be held liable for compensation such as loss of use or delays.

2. Some insurance companies shift their responsibilities to the victims

In truth, arranging a repair shop is the insurer’s responsibility, not the car owner’s.

But what happens is that many victims, afraid their cars will not be repaired, sign whatever the repair shop asks. As a result, they go from being a victim of the accident to becoming a victim of the insurance process as well.

Did You Know? You Have the Right NOT to Sign

Under general insurance principles, if the policy does not require a signature, the car owner has no obligation to sign anything, including:

  • Repair timeframe consent forms
  • Consent to use aftermarket/non-OEM parts
  • Consent to send the vehicle to a specific repair shop

Paying your insurance premium means:

➡ The insurer must provide service and convenience—not impose additional burdens.

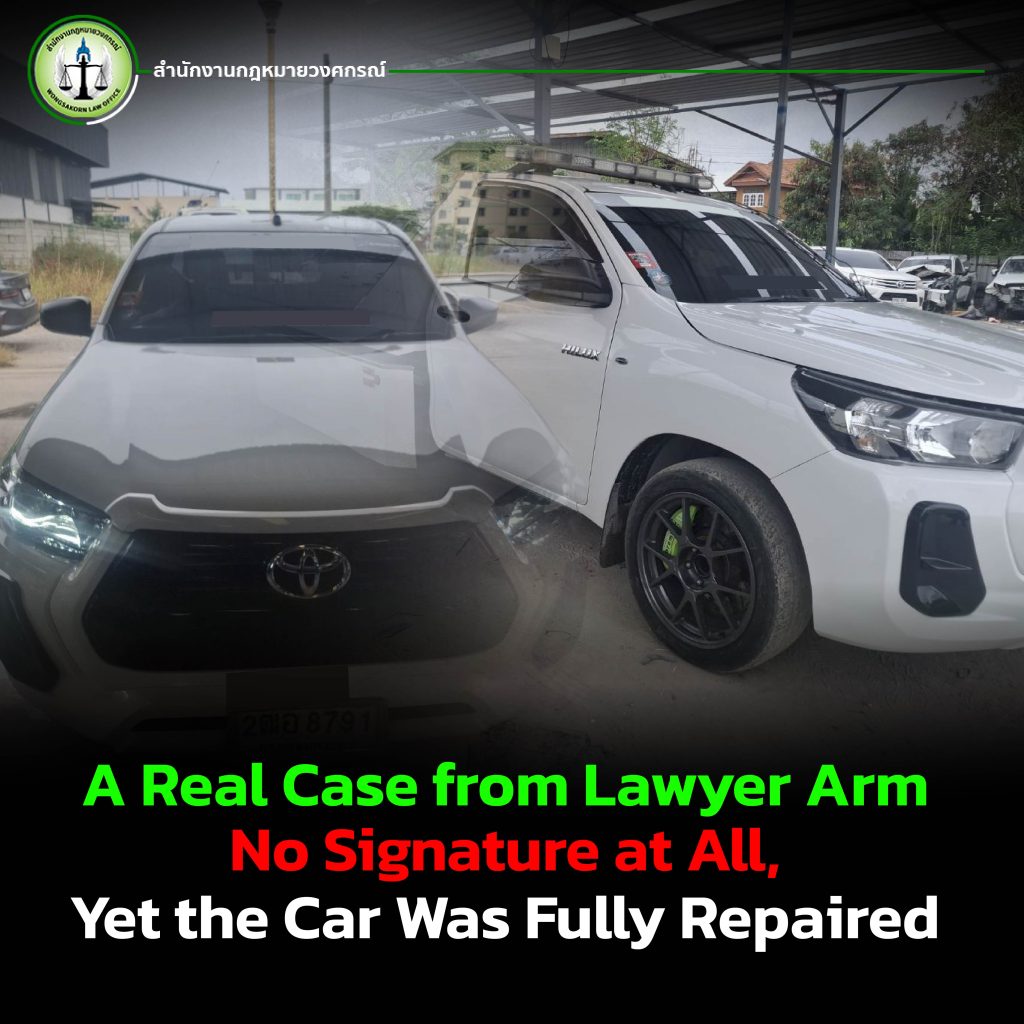
A Real Case from Lawyer Arm: No Signature at All, Yet the Car Was Fully Repaired

In a recent case involving Lawyer Arm’s own company car, an employee driving the vehicle was involved in an accident. When the car was sent to a repair shop, the shop said:

“If the owner or Lawyer Arm does not sign to acknowledge a repair period of more than 15 days and agree to the use of a mix of genuine and non-genuine parts, the shop will not repair the car.”

Most victims would rush to sign out of fear that the repair shop might refuse to fix their car. However, Lawyer Arm emphasizes that the insurance policy contains no such requirement, and neither the insurance company nor the repair shop has the authority to force victims to sign documents not specified in the policy.

Because Lawyer Arm specializes in insurance litigation, he did not sign anything or contact the repair shop further knowing that the repair shop was legally required to complete the repair without such conditions.

And finally, the repair shop itself called to inform Lawyer Arm that the car was ready for pickup.
The vehicle was fully repaired without a single signature.

This case clearly shows that if victims do not know their rights and follow everything the repair shop or insurance company says, they may become victims without realizing it.

Why Do Victims Usually Lose Against Insurance Companies?

Because…

➡ Insurance companies have lawyers before the accident even happens, but victims have no one.

Insurance companies have legal teams trained to minimize liability. Victims who lack legal knowledge are easily misled, pressured, or provided incomplete information, causing them to sign documents they shouldn’t.

This is why many people become double victims:
– Their car is damaged
– They lose time
– They lose money
– And they unknowingly lose their legal rights

Meanwhile, insurance companies can simply deny liability.

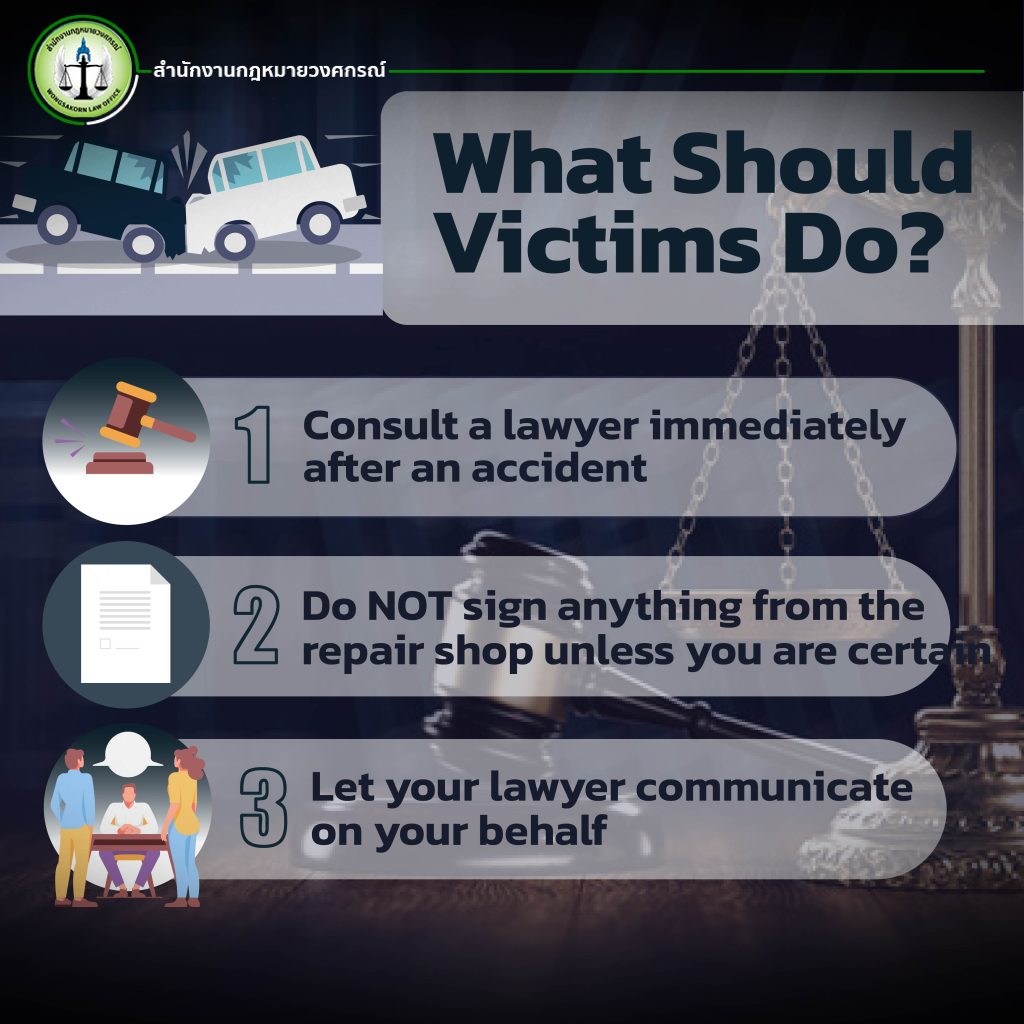
✔ Consult a lawyer immediately after an accident
A lawyer can assess your rights, damages, and the correct procedures.
Even one mistake can give insurers grounds to deny compensation.

✔ Do NOT sign anything from the repair shop unless you are certain
Especially documents not mentioned in your policy.

✔ Let your lawyer communicate on your behalf
This prevents pressure, manipulation, or misinformation from repair shops or insurers.

Key Takeaways Every Car Owner Must Remember

Because no one should suffer due to not understanding insurance company tactics

1) Repair shops have no authority to force you to sign

If it’s not in your policy, you are not required to sign anything.

2) Insurance companies must provide service not burden you

Finding a repair shop is the insurer’s responsibility.

3) Not knowing your rights = Disadvantage

Insurers have legal teams; victims often have none.

4) Handling the claim alone can worsen the situation

You may receive less compensation than you deserve or nothing at all.

5) Having a lawyer from the beginning reduces the risk of denied claims

Every step impacts your legal rights.

If You’re Having Problems with a Repair Shop

Or if an insurance company is asking you to sign documents you’re unsure about…

Do NOT wait until your claim is denied.
Do not handle everything alone and risk getting nothing.

Wongsakorn Law Office is ready to protect victims from being taken advantage of by insurance companies.
No one should lose simply because they don’t understand the insurer’s tactics.

📞 Contact us today: 062-195-1661

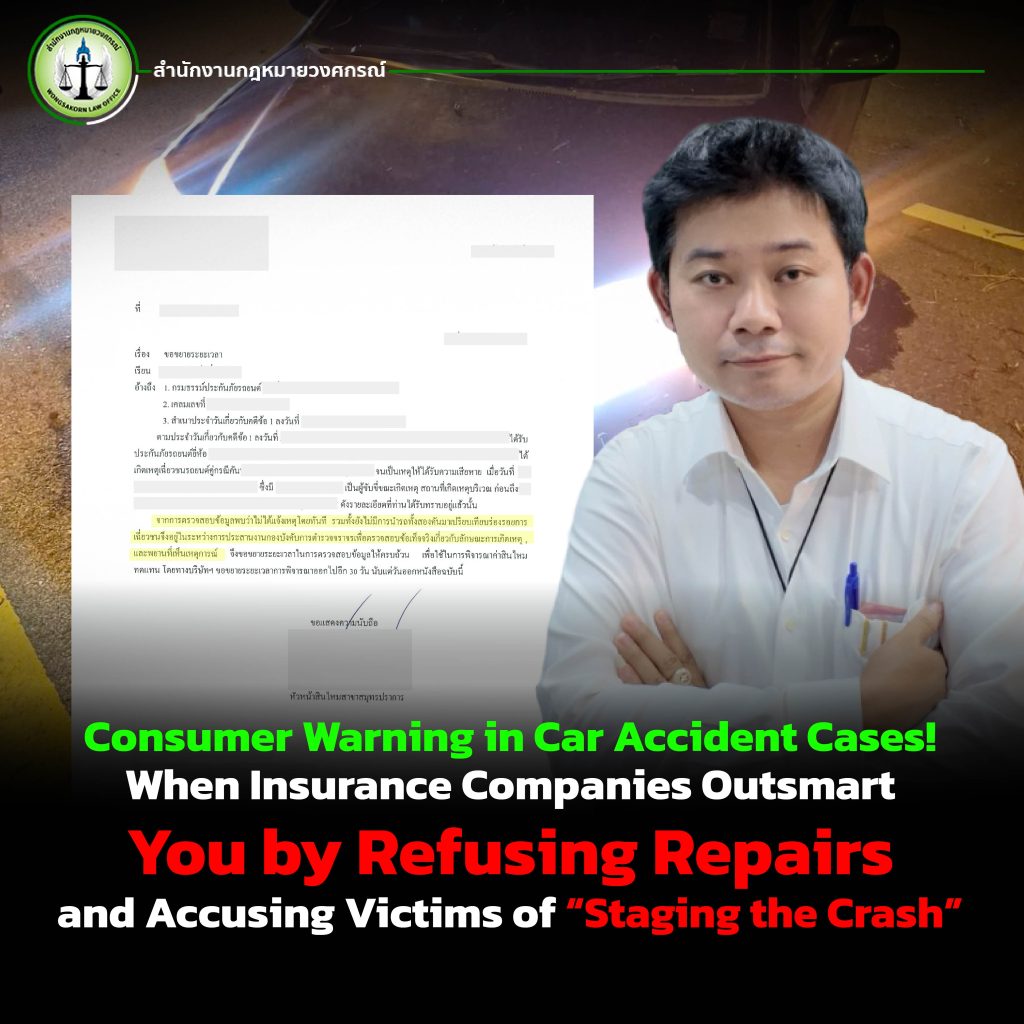
Consumer Warning in Car Accident Cases! When Insurance Companies Outsmart You by Refusing Repairs and Accusing Victims of “Staging the Crash”

As car accident cases continue to rise, many consumers still believe that once an accident occurs, the insurance company will handle everything, arranging repairs, assessing damage, and compensating the injured party fairly. Unfortunately, reality is far from this assumption. Many insurance companies adopt strategies to avoid responsibility: refusing to repair, claiming documents are incomplete, or even alleging that the victim contributed to the incident.

One such case involves an elderly woman, a case that has now become an important lesson for all consumers regarding their rights in car accident disputes.

Insurance Company Ignored the Case for 2 Full Months No Repairs, No Assessment, No Response

The incident began when the elderly woman’s car was hit and severely damaged. Instead of arranging repairs as required, the at-fault driver’s insurance company did nothing.
For two months, they:

  • did not contact her,
  • did not assess the damage,
  • did not bring the vehicle in for repair.

The woman, who had no legal knowledge, had no idea what to do. People around her advised her to file a complaint with the OIC (Office of Insurance Commission). However, it is widely known that the OIC often works in ways that lean toward supporting insurance companies. Starting the process this way may cause unnecessary delays and potential loss of rights.

Fortunately, she had not filed the complaint yet and instead chose to consult the Lawyer Arm from Wongsakorn Law Office.

Lawyer Arm Immediately Took Over the Case and Issued a Formal Notice Demanding Repairs

After reviewing all the details, Lawyer Arm found that the case carried a high risk of the insurance company misleading the victim or avoiding responsibility.

The office immediately drafted and sent a formal letter to the insurance company instructing them to:

  • bring the damaged vehicle in for repair,
  • restore it to its pre-accident condition,
  • fulfill all duties required under the insurance policy.

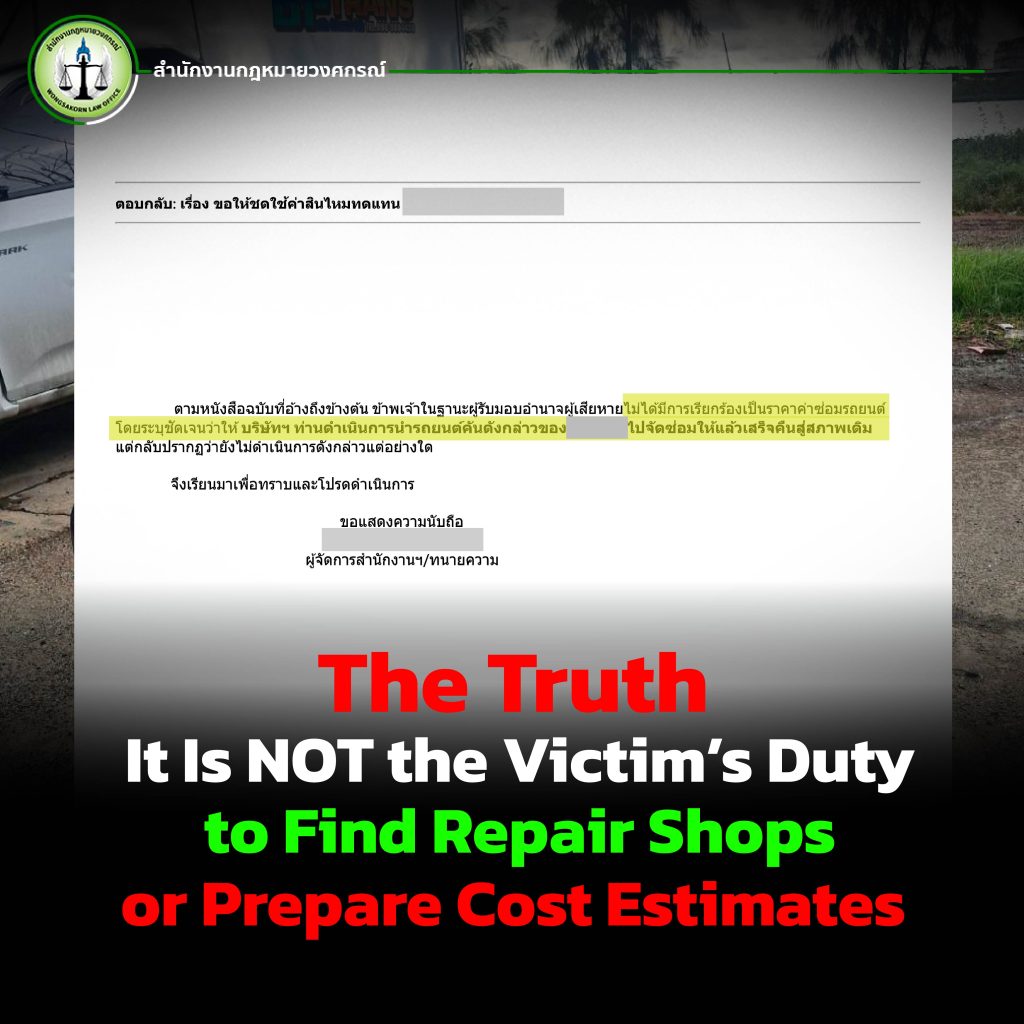
Importantly, the letter did NOT demand any repair costs from the insurance company; it merely required them to take the car and repair it, as the responsible insurer.

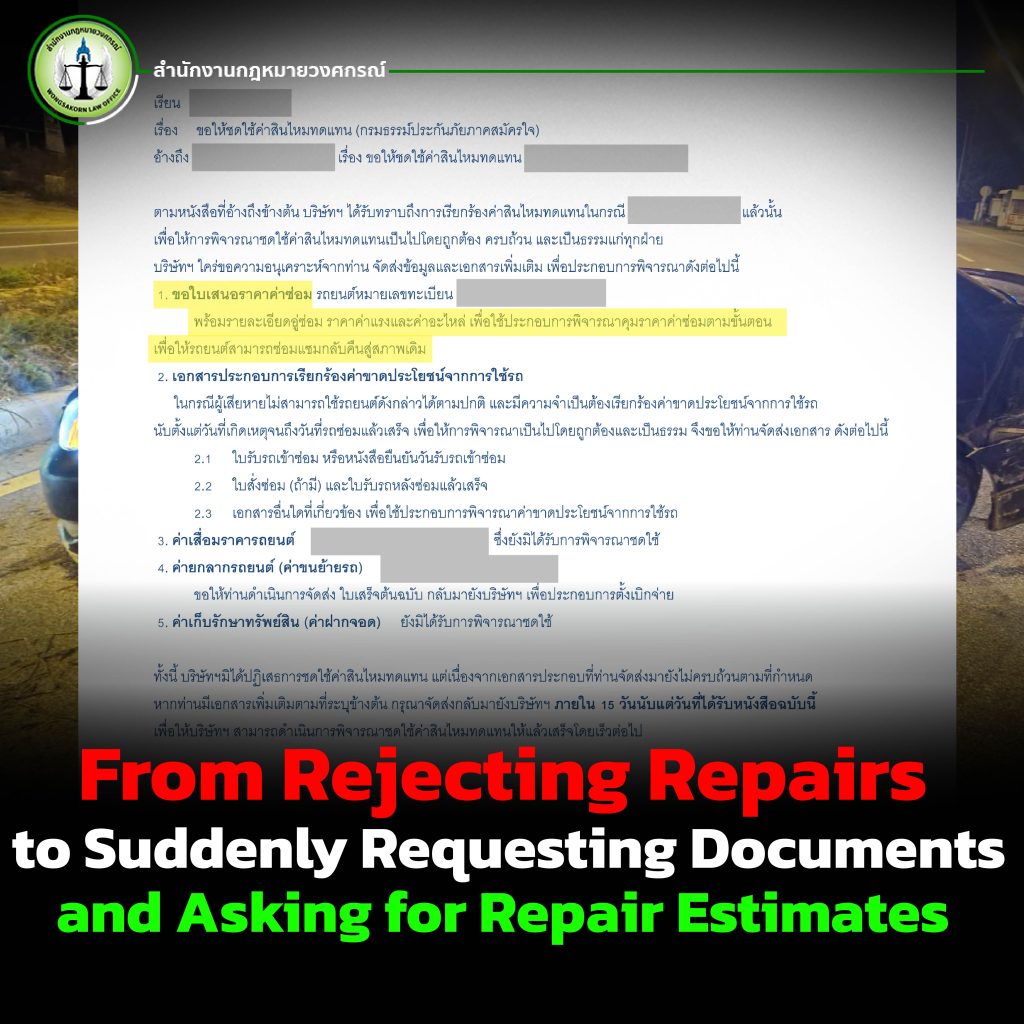
From Rejecting Repairs to Suddenly Requesting Documents and Asking for Repair Estimates

After receiving the letter, the insurance company shifted their attitude and responded by requesting:

  • repair cost estimates,
  • repair shop details,
  • labor costs,
  • parts pricing,

which they claimed were needed for “price control procedures.”

Although it might sound reasonable, in reality…

 This is a strategy designed to shift responsibility onto the victim.

Why Did the Lawyer Advise “Do NOT Prepare Repair Estimates”?

According to Lawyer Arm, preparing repair estimates poses high risks, because the insurance company could later accuse the victim of:

  • providing a fake estimate,
  • listing incorrect parts,
  • inflating prices,
  • adding unnecessary items.

They could even file a counter-lawsuit against the victim, claiming attempted fraud.

Most consumers have no idea this can happen.

The Truth: It Is NOT the Victim’s Duty to Find Repair Shops or Prepare Cost Estimates

In car accident and insurance law:

  • The insurance company must manage all repair arrangements.
  • The insurance company must select the repair garage.
  • The insurance company must assess repair costs.
  • The insurance company must restore the car to its original condition.

The victim has zero responsibility to prepare repair estimates.

Therefore, the insurance company’s attempt to push this duty onto the victim is a clear violation of proper procedure.

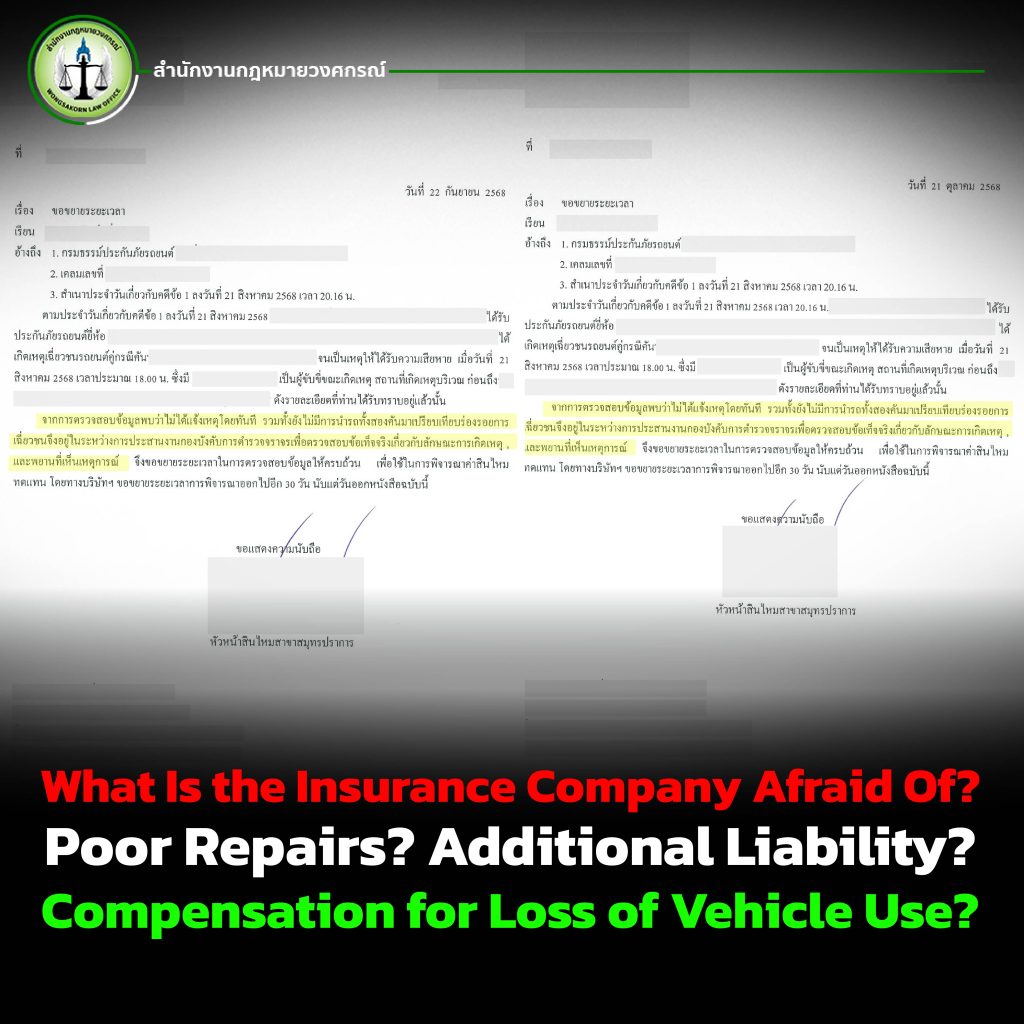
What Is the Insurance Company Afraid Of? Poor Repairs? Additional Liability? Compensation for Loss of Vehicle Use?

Many people wonder:

  • Are they afraid repairs will not meet standards?
  • Are they afraid they will incur additional liability if problems arise later?
  • Are they afraid they will have to pay loss of vehicle use compensation while the car is being repaired?

Regardless of the reason, the victim should not be forced to bear these burdens.

Main Lesson: Consumers Need a Lawyer Because Insurance Companies Already Have Lawyers Before the Crash Even Happens

Most people do not realize:

Insurance companies already have lawyers prepared before any car accident occurs.
They have time, legal resources, and strategies ready to reduce liability.

But consumers usually:

  • have no legal advisor,
  • have no knowledge of their rights,
  • lack experience dealing with insurance tactics.

Thus, when an accident occurs, consumers should consult a lawyer to:

  • protect their rights,
  • prevent unfair treatment,
  • compel the insurance company to fulfill its duties,
  • avoid being pushed into taking responsibility for things they shouldn’t.

Don’t Let Insurance Companies Manipulate Your Rights

This case shows how some insurers may:

  • reject repairs altogether,
  • accuse the victim of staging the crash,
  • demand documents the victim is not responsible for,
  • twist procedures to avoid paying compensation.

Consumers must stay informed and have a professional to protect their interests.

If you are facing a car accident dispute, if your insurance company refuses repairs, or if you feel the company is avoiding responsibility:

👉 Consult Lawyer Arm – Wongsakorn Law Office
📞 Tel: 062-195-1661

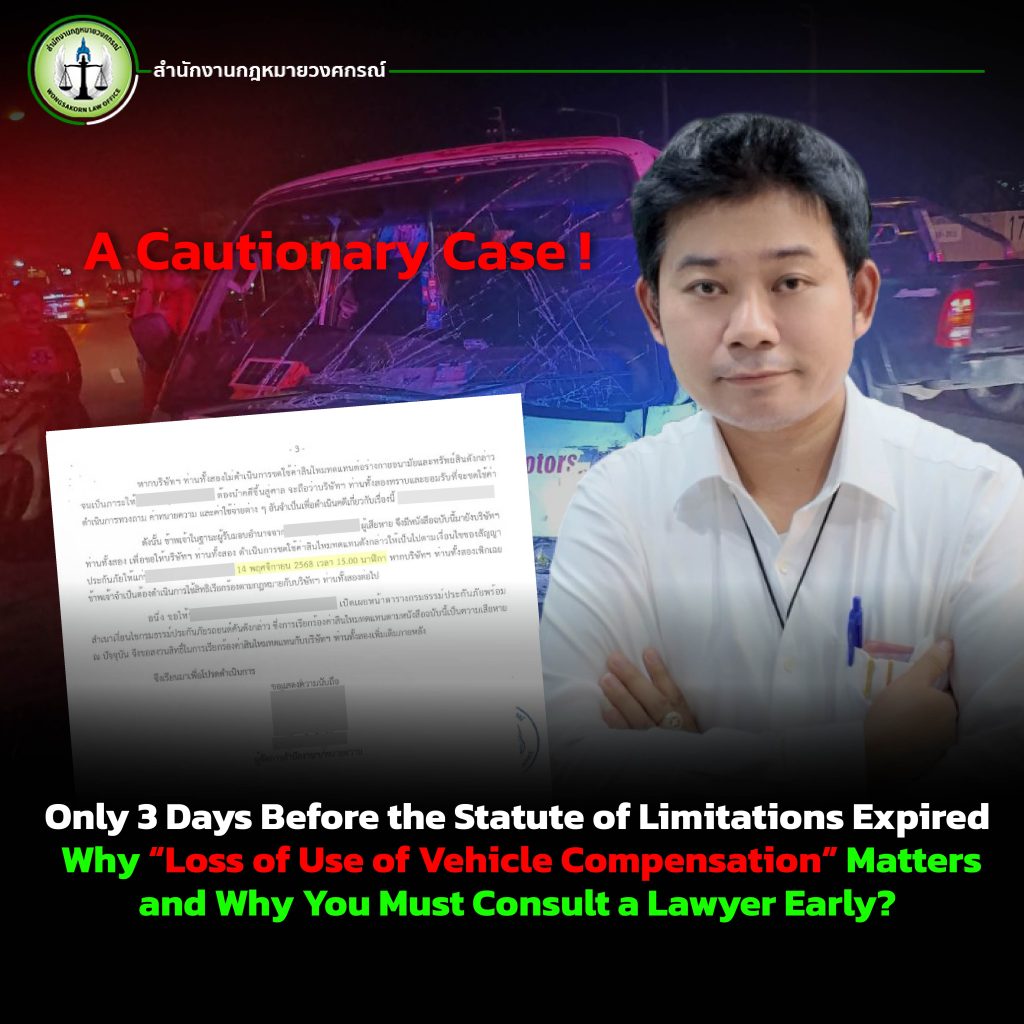
A Cautionary Case: Only 3 Days Before the Statute of Limitations Expired: Why “Loss of Use of Vehicle Compensation” Matters and Why You Must Consult a Lawyer Early?

When a car accident occurs and your vehicle is damaged to the point that it cannot be used, one type of compensation that many victims often overlook is “loss of use of vehicle” compensation. This is a legal right that every victim is fully entitled to claim. However, in reality, many people never receive this compensation because they do not know their rights or they wait until the statute of limitations is almost over.

This is a real case involving Mr. A, which has now become an important reminder for every driver.

Only 3 days left before the statute of limitations expired and still no response from the insurance company

Mr. A was involved in a serious accident nearly two years ago. His car was severely damaged and unusable. Legally, he was entitled to:

  • Repair costs
  • Towing fees
  • Compensation for damaged property
  • And most importantly: loss of use of vehicle compensation

But almost two years passed, and the insurance company:

  • Never contacted him
  • Never informed him of any progress
  • Never paid a single baht

Why?

Because…

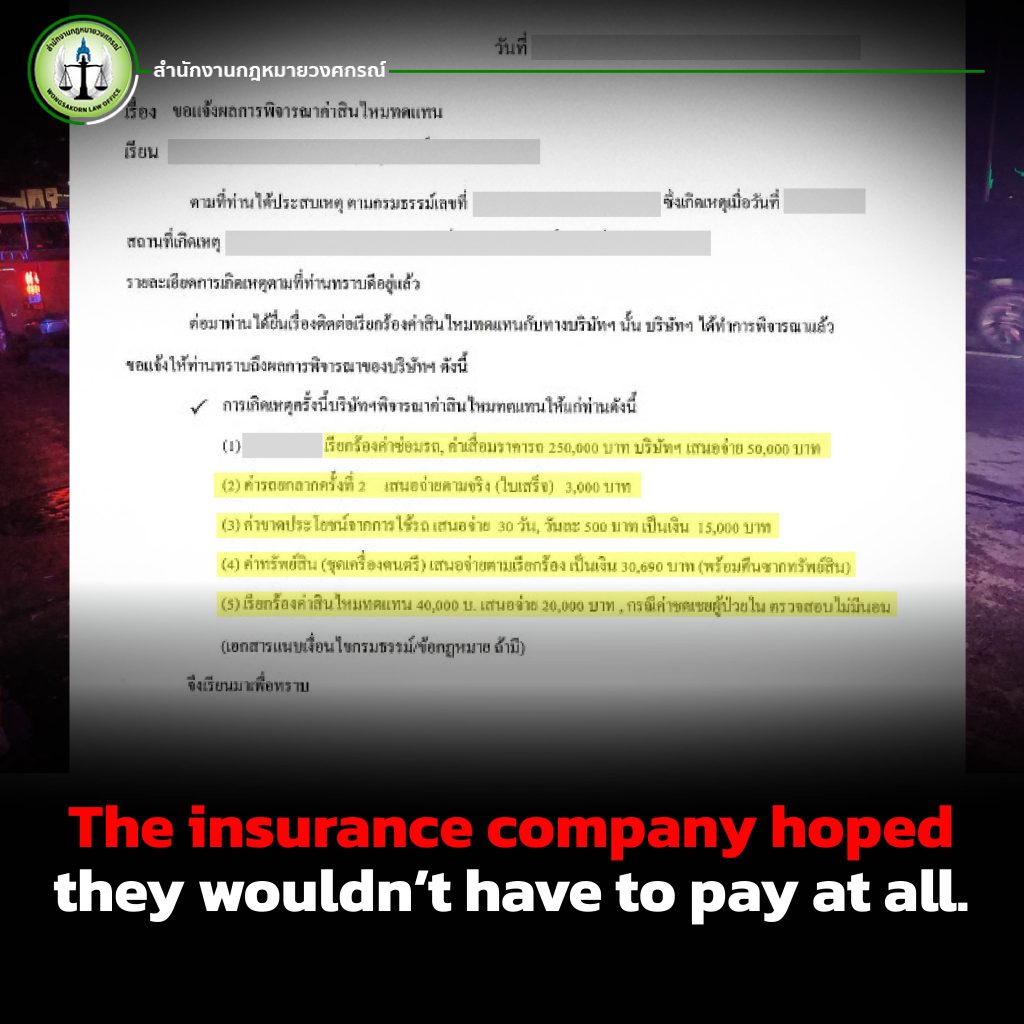
The insurance company hoped they wouldn’t have to pay at all.

If the statute of limitations expired, the company would not have to pay anything.

The expiration date fell on the 17th, which was a Sunday meaning there was practically no time left to file anything.

If Mr. A had not urgently consulted a lawyer, everything would have been lost forever.

This is something most drivers do not know.

But it is exactly what insurance companies hope will happen.

The beginning of the problem: The insurer claimed “This car model has no repair shop available.”

The insurer told Mr. A:

“This car model has no authorized repair center.”

But legally, it is not the vehicle owner’s responsibility to find a repair shop. It is the insurance company’s duty to fix the vehicle and return it to normal condition.

Insurance companies cannot escape liability by giving excuses like this.
However, many victims do not know the law, and therefore unknowingly accept unfair treatment.

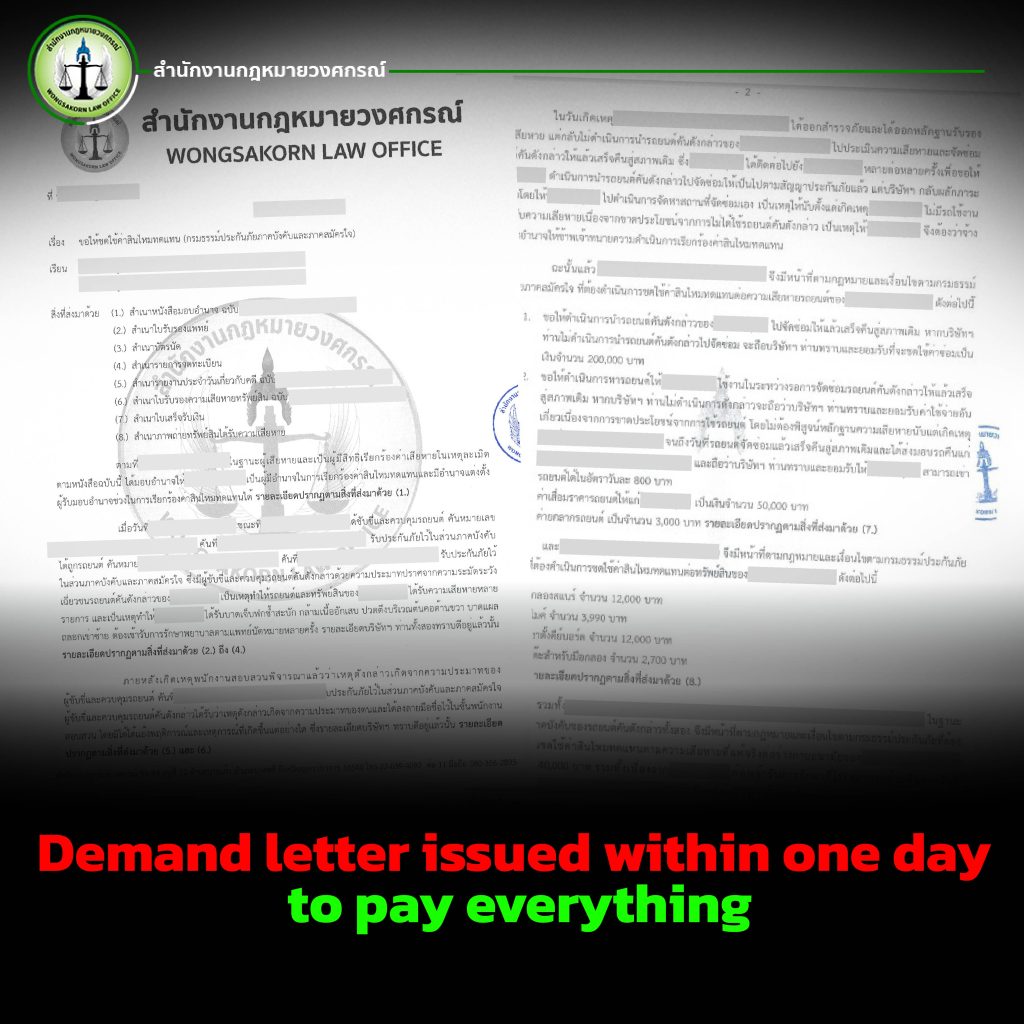
Demand letter issued within one day and the insurer immediately agreed to pay everything

Many lawyers might have told him to wait 3–7 days, or follow the standard insurance procedures.

But waiting in this case meant the statute of limitations would expire, and Mr. A would get nothing.

Lawyer Arm from Wongsakorn Law Office acted immediately:

  • Prepared and issued an urgent demand letter
  • Stated clearly:
    “Provide compensation by 3:00 PM today.”

What many would think is “impossible”… actually happened.

The insurance company responded and agreed to pay all claimed damages immediately.

No further review. No additional procedures.This means the insurer could have done this all along, but simply chose not to for almost two years.

The insurance company offered full compensation including loss of use of vehicle

After receiving the demand letter, the insurer agreed to pay all damages, including:

  • ✔ Car repair costs
  • ✔ Towing costs
  • ✔ Property damage
  • ✔ Loss of use of vehicle
  • ✔ Additional related damages

Totaling over 100,000 THB.

This happened simply because the case was handled before the statute of limitations expired, and legal action was taken promptly.

What is loss of use of vehicle compensation, and why is it so important?

This compensation covers the period when your car cannot be used, such as:

  • Cost of renting a replacement vehicle
  • Additional transportation expenses
  • Loss of income if the car is used for business

Even if you did not actually rent a replacement car, you can still claim compensation based on standard court rates.

But many people never receive this compensation because:

  • They don’t know their rights
  • They never file a demand
  • They have no lawyer assisting
  • They let the statute of limitations expire

This case is a major lesson never wait until the last minute

Mr. A drove all the way from Prachinburi to meet Lawyer Arm. Thankfully, he still had 3 days left.

But many victims are not as lucky.

Reasons why people lose their right to compensation:

  • They assume the insurance company will “handle everything”
  • They are afraid of consulting a lawyer
  • They don’t know when the statute of limitations ends
  • They simply let time pass

Important truth: Insurance companies “have lawyers from day one even before the accident happens.”

Insurance companies have a full legal team ready at all times.

Ordinary people usually have no legal guidance, which puts them at a major disadvantage.

That is why victims should:

Consult a lawyer immediately on the day the accident happens.

Doing so helps you:

  • Understand your rights
  • Avoid being misled
  • Know exactly what damages you can claim
  • Prevent the statute of limitations from expiring

Don’t let insurance companies get what they hope for. Consult a lawyer from day one.

Mr. A’s case ended successfully, with full compensation received.
But only because:

  • He still had 3 days left, and
  • He decided to seek legal help in time

If you have been waiting for an insurance response…
If it has already been months or years…
If you don’t know where to start…

Do not wait another day.

Once the statute of limitations expires, you lose everything.

Consulting a lawyer early is the only way to protect your rights and ensure you receive:

  • Loss of use of vehicle compensation
  • And all other damages you are legally entitled to

Contact us at Wongsakorn Law Office to get proper legal support today.

Lawyer Arm Shares a Real Experience: “Car Repair Shop” Forced Him to Sign Repair Duration Agreement or They Wouldn’t Fix the Car!

A car repair shop is something every car owner has to deal with at some point especially after an accident. But surprisingly, even if you already have car insurance, many consumers still fall victim to the practices of certain repair shops and insurance companies without realizing it.

Recently, Lawyer Arm shared a real-life experience that happened to him. One of his employees accidentally crashed his car, and when he brought it in for repairs, something shocking happened. In this article, Lawyer Arm aims to raise awareness and warn the public:
If you don’t understand your rights or have a lawyer guiding you from the beginning, you could easily be taken advantage of by the repair shop or the insurance company.

The Repair Shop Called and Demanded a Signature Before Continuing the Repair

After the accident, Lawyer Arm’s car was sent to an insurance-affiliated repair shop. One day, the shop called and said:

“You must sign to accept the repair period and waiting time for parts. If you don’t sign, we can’t continue fixing your car.”

It might sound like a standard request for customer acknowledgment, but for someone who knows the law, Lawyer Arm immediately recognized this was not in line with OIC (Office of Insurance Commission) regulations.

OIC Clarifies: “Notification” Doesn’t Mean “Signature Required”

According to the OIC’s official regulation, “notifying the insured” means informing them not requiring a signature.

Notification can be done through:

  • Phone call
  • Email
  • LINE message
  • Written document or repair report

The intent is simply to update progress, not to make customers accept unfair conditions, such as excessive waiting periods or the use of mixed genuine and imitation parts.
However, in this case, the repair shop twisted the rule, turning a simple “notification” into a forced signature, which is both misleading and unfair to consumers.

The Problem with Mixing Genuine and Imitation Parts

Besides forcing a signature, the repair shop also said:

“We’ll use both genuine and imitation parts.”

At first, this might sound like a compromise but in legal and professional terms, repairs must restore the vehicle to its pre-accident condition as closely as possible.

Lawyer Arm explained:

“It’s simple if your car originally had genuine parts, the repair should use genuine parts. Mixing parts reduces quality, safety, and future resale value.”

If the repair shop must wait for genuine parts, they only need to notify the customer, not force them to sign anything. Refusing to continue repairs unless you sign is a clear violation of regulations.

What to Do If the Repair Shop Refuses to Fix Your Car?

Lawyer Arm recommends consulting a lawyer immediately if you face such a situation. A lawyer can communicate directly with the insurance company and document the shop’s refusal properly, for instance, by email or chat to preserve evidence in case of future disputes.

Understand Clearly  “Notify” ≠ “Sign”

Many people confuse the two terms. Lawyer Arm clarifies:

“‘Notify’ doesn’t mean signing acknowledgment, nor does it release the repair shop from responsibility for delays. It’s just a progress update, not an agreement to delay.”

So, if a repair shop says, “If you don’t sign, we won’t fix your car,” you have the right to refuse and report the matter to your insurance company immediately.

Why Having a Lawyer Matters from the Moment of the Accident?

Lawyer Arm’s real experience shows that even someone knowledgeable about the law can face unfair treatment without proper legal representation.
Both the repair shop and the insurance company might interpret regulations in their own favor, not yours.

Without a lawyer to guide you from the start, you risk losing your rights without realizing it.
In reality, “If you don’t have a lawyer from the moment of the accident, you can easily be taken advantage of.”

Know Your Rights Before You Sign Anything

This case perfectly illustrates why understanding the law and OIC regulations protects consumers.
If any repair shop or insurance company pressures you to sign documents or accept unclear conditions don’t hesitate to consult a lawyer.

Because at the end of the day:

“The insurance company always has their lawyer. Do you have yours?”

📞 Contact: 062-195-1661 | Click to Consult a Lawyer Now

“Car Depreciation After an Accident” Why Insurance Companies Refuse to Pay, and Why You Need a Lawyer to Get Your Rights Back?

When a car accident occurs, most vehicle owners face not only physical or property damage but also the long and often frustrating process of claiming compensation from their insurance company.
One of the most debated issues is “car depreciation” after repairs does the insurance company have to pay for it?The answer is yes it can be legally claimed.
However, in reality, insurance companies often refuse to pay.
As a result, many victims have to rely on experienced insurance lawyers to claim their rightful compensation.
That’s because “car depreciation” isn’t something anyone can simply demand; it requires legal knowledge, technical evidence, and professional strategies to prove the true loss in value.

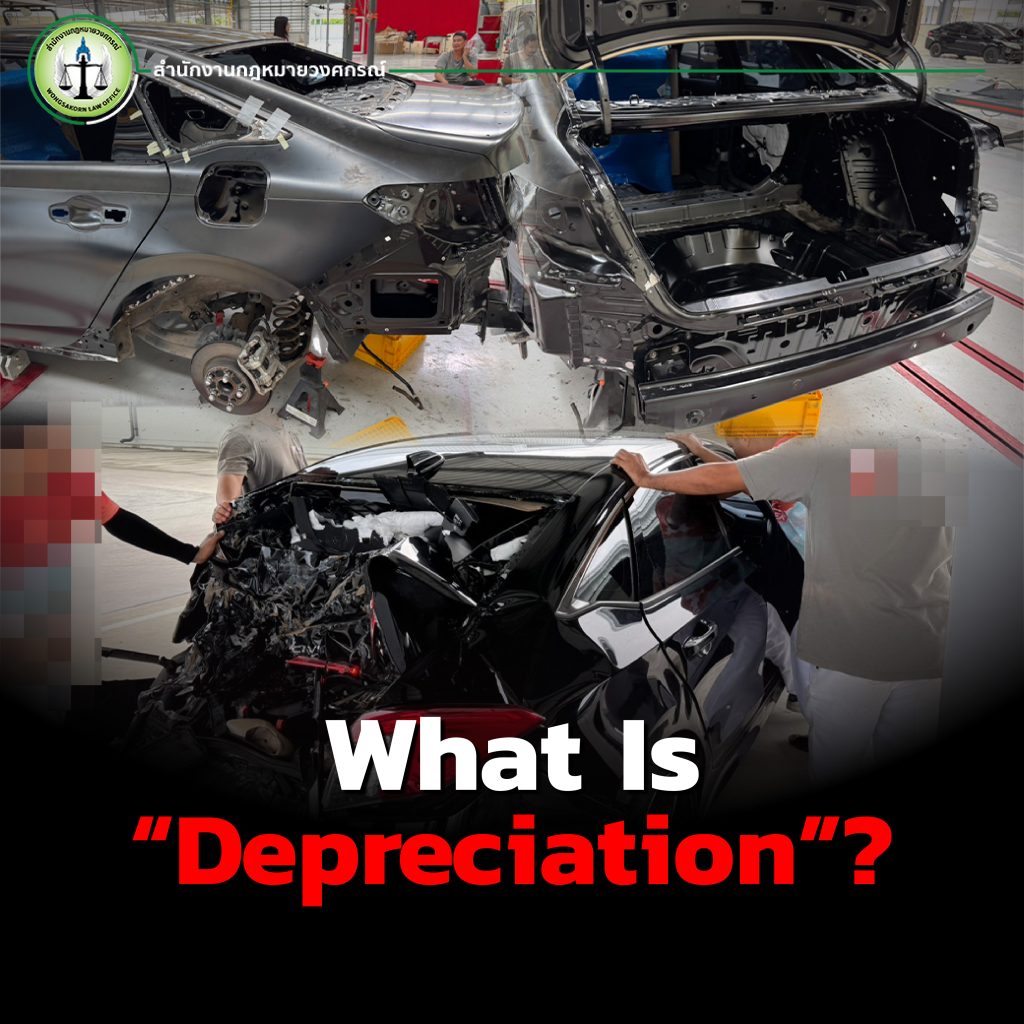
What Is “Depreciation”?

Depreciation refers to the loss in value of a property after an accident.
Even if a car has been perfectly repaired, its market value is no longer the same.
In the used car market, a vehicle that has been in an accident always sells for less than one that hasn’t.

For example, if your car was worth 1,000,000 THB before an accident, and after repair you can only sell it for 900,000 THB,
The 100,000 THB difference represents the “depreciation value” , a real financial loss that you have the right to claim from the insurer or the at-fault party under Thai law.

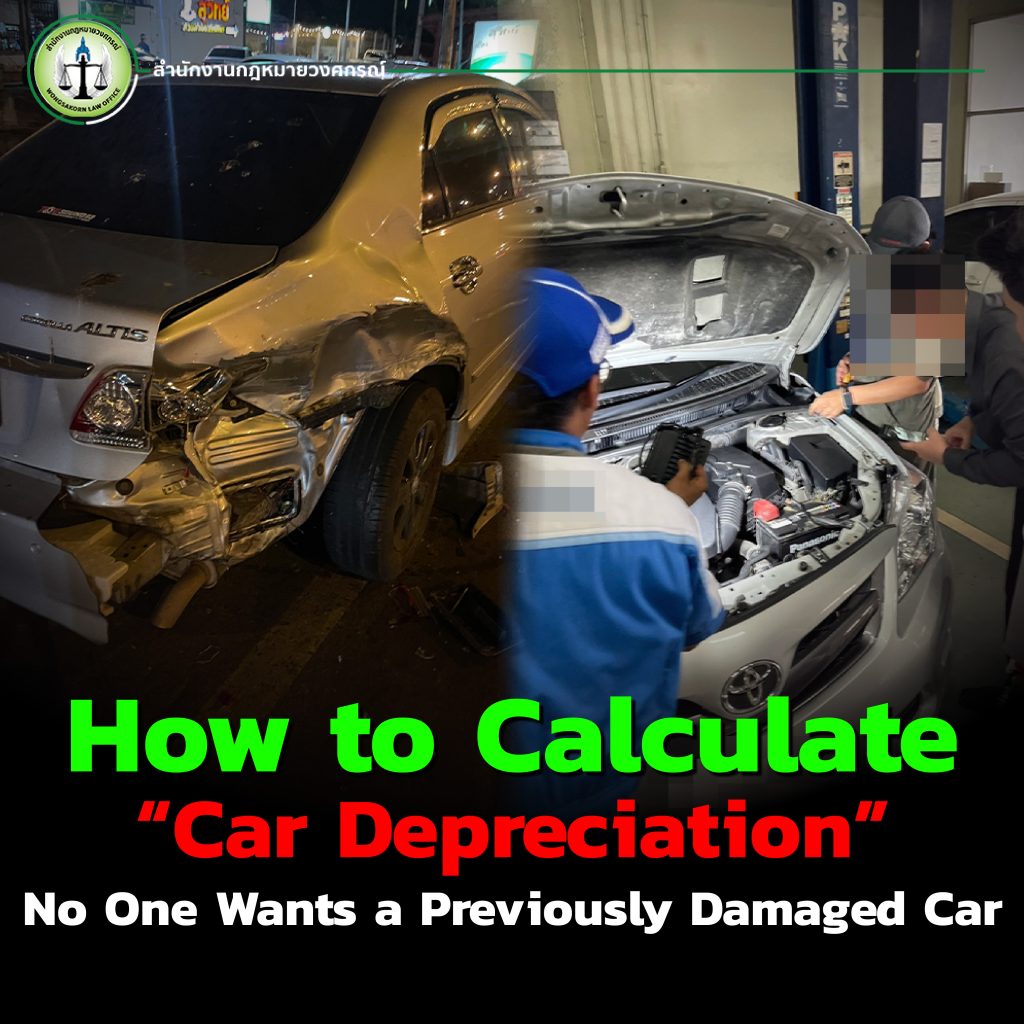
How to Calculate “Car Depreciation” No One Wants a Previously Damaged Car

Even after a full repair, a damaged car will never be the same. Its value drops that drop is what we call “depreciation.”
According to Lawyer Arm, there are three main methods to assess car depreciation:

Method 1 – Based on Real-Life Sales

A client who ran a used car business got into an accident while driving to meet a buyer.
The customer refused to buy the car after learning it had been in an accident, saying, “No one wants a crashed car.”
Originally priced at 500,000 THB, the buyer offered only 100,000 THB.
👉 The 400,000 THB difference was the actual depreciation caused by the accident.

Method 2 – Appraisal from Used-Car Dealers

Sometimes, the victim can ask car dealers to appraise the price difference.
For example, a dealer might say that a certain model usually sells for 500,000 THB, but if it’s been in an accident, they would only buy it for 200,000 THB.
👉 The 300,000 THB difference also represents the depreciation value.

Method 3 – Assessment by Certified Experts or Mechanics

If there’s no real transaction, an expert mechanic or auto body specialist can assess the car’s post-repair value based on comparable models in the market.
👉 This method is fair, transparent, and technically verifiable.

Key Points from Lawyer Arm

  • Claiming depreciation is a legal right because an accident reduces your vehicle’s market value.
  • Insurers must not advise victims to lie to car dealers that the vehicle has never been in an accident that’s unethical.
  • In reality, no one wants to buy a heavily damaged vehicle, and resale value inevitably drops.

Depreciation is therefore a real and provable loss, and victims are entitled to compensation under the law.

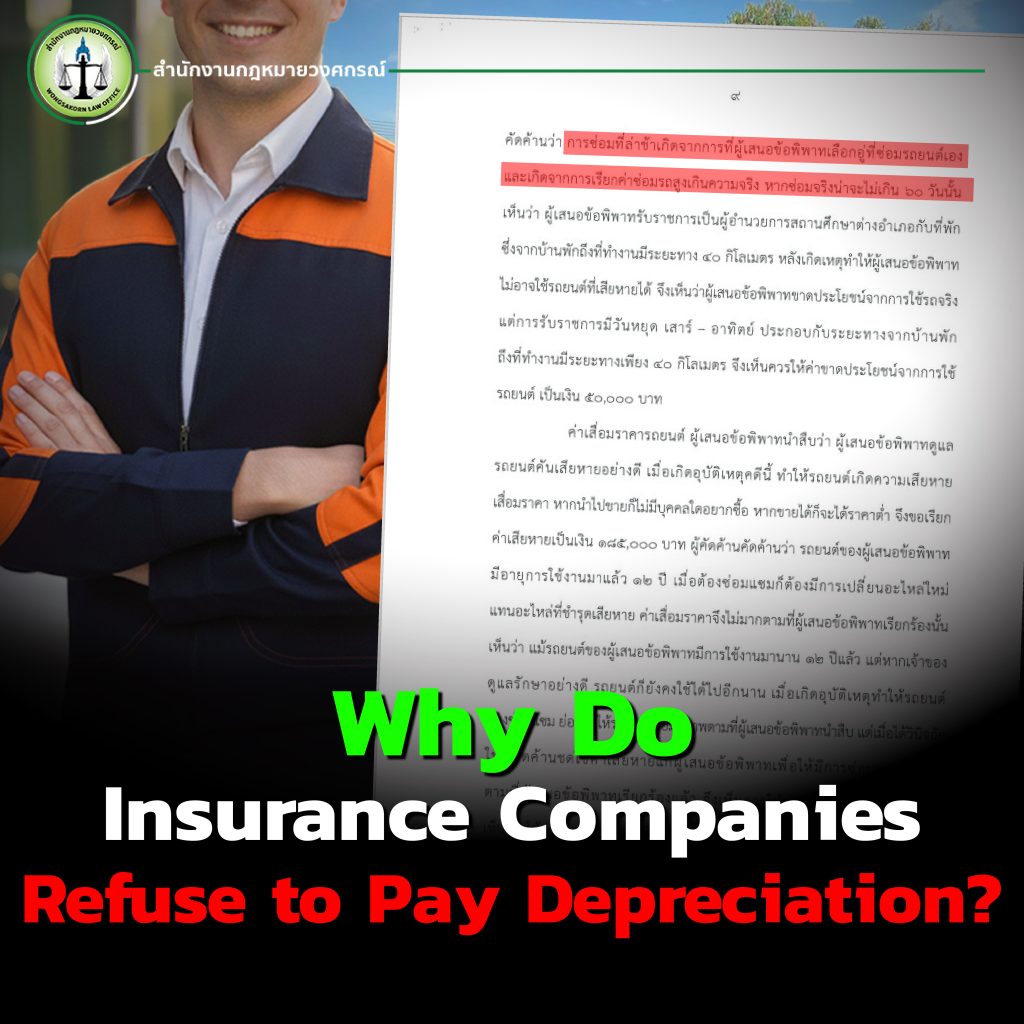
Why Do Insurance Companies Refuse to Pay Depreciation?

Even though depreciation is a real loss, insurance companies often deny the claim using reasons such as:

1.The repaired car is “as good as new.”

2.There’s no market evidence supporting the price drop.

3.The insurance policy doesn’t explicitly mention depreciation coverage.

But legally, depreciation does not need to be stated in the policy.
If you can prove the loss in value, the company must compensate under Civil and Commercial Code Section 420 (tort law).

 Why Should Have a Lawyer Handle the Claim?

While victims can technically file claims themselves, proving depreciation requires strong, technical evidence, such as:

  • Pre- and post-repair valuation reports
  • Expert witness opinions
  • Repair receipts and documents
  • Photographs of the damaged car

A lawyer’s role is crucial in:
✅ Assessing the true financial loss
✅ Preparing admissible evidence for court
✅ Referencing previous court rulings on depreciation to strengthen your case

Simply put:
If the insurance company has a legal team before the crash even happens,
then you should also have your own lawyer from the moment the crash occurs.

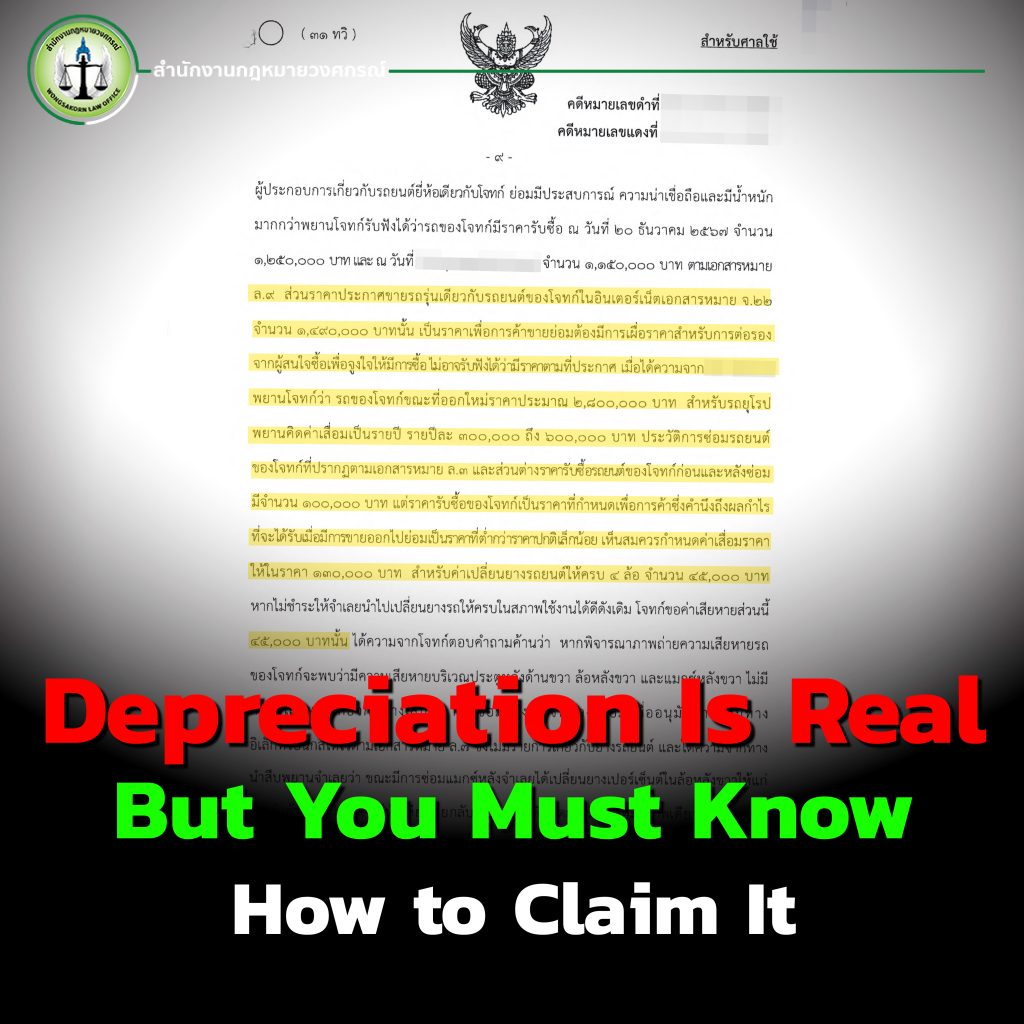
Depreciation Is Real But You Must Know How to Claim It

Car depreciation is not a bonus or a favor from the insurer, it’s a real, lawful damage you deserve to recover.
Unfortunately, many people lose this right because they don’t know how to claim it properly.

If your insurer refuses to pay for car depreciation, don’t stay silent.
Consult a lawyer immediately to ensure your rights are fully protected.

 Wongsakorn Law Office, led by Lawyer Arm, specializes in car insurance cases including repair costs, loss of use, and depreciation claims.
We’re ready to fight for your rightful compensation in every step of the process.
Consult a lawyer today → Contact Us or call 062-195-1661.

Does an Insurance Company Have the Right to Choose a Lump-Sum Repair for the Customer’s Car?

The answer is “Yes” But not at the expense of the customer’s rights.

When a car accident happens, many insured drivers feel reassured knowing that their insurance company will handle the repair costs. However, what most policyholders don’t realize is that insurance companies can manage car repairs in several ways. One common practice is “lump-sum repair” or “contracted repair,” where the insurer negotiates a fixed amount with a repair shop. This often leads to dissatisfaction among customers who feel their cars were “not restored to their original condition” or “poorly repaired.”

So, does an insurance company have the right to do this?
Legally, yes, they do but that right must remain within reasonable limits and must not cause harm to the insured party. The goal of repairing the customer’s car should be to restore it to its original condition, not to cut costs for the company’s own benefit.

Understanding “Lump-Sum Repairs” in the Insurance Industry

A “lump-sum repair” means the insurer estimates the total repair cost and agrees on a fixed price with a repair shop or service center often without consulting the customer. For example, if your car sustains 40,000 baht in damages, the company might strike a deal with a garage for that amount, leaving you out of the decision-making process.

While this may sound reasonable from a business perspective  as insurers must control costs in practice, this often leads to cost-cutting repairs rather than quality restoration.

Common problems include:

  • Incomplete or substandard repairs
  • Use of second-hand or non-genuine parts
  • Paintwork that doesn’t match the original
  • Or worst of all recurring issues requiring multiple repair attempts

Even though insurers have the right to choose lump-sum repairs, they do not have the right to infringe upon the customer’s legal rights.

The Customer’s Legal Right: “Restoration to the Original Condition”

Under motor insurance principles, repairs after an accident must restore the vehicle to its pre-accident condition.
 That means your car should be as close as possible to its original state in terms of structure, paint quality, safety, and functionality.

If an insurer’s chosen repair method worsens the car’s condition or reduces its quality, that could amount to a “tortious act.”
 An insurer cannot act in bad faith under the contract to the detriment of the insured.

Legally, even though the insurer is a contracting party, this doesn’t grant them unlimited authority over your vehicle.
Customers are entitled to fair, quality repairs that return their property to its original state. Acting solely for the company’s financial gain is not legally justifiable.

Lawyer Arm’s View: “Yes, They Can  But Not at the Customer’s Expense”

Lawyer Arm explains:

“The insurer may have the right to choose lump-sum repairs, but they have no right to cause the customer further harm.”

The insurer’s right to manage operations is protected by law, but it must be exercised in good faith and responsibility  consistent with Section 420 of the Thai Civil and Commercial Code, which states:

“A person who, willfully or negligently, unlawfully injures another is bound to make compensation.”

If the insurer’s repair decision leads to further damage such as mismatched paint, reduced performance, or new mechanical issues that could constitute a tort.

Moreover, a car is not just a financial asset it directly relates to safety. Poor-quality repairs may not only devalue the car but could cause further accidents, making the insurer liable under civil or even criminal law.

Why Should You Consult a Lawyer from the Start?

When an accident occurs, and your car needs repair, the first thing you should do is ask for clarity upfront:
 Where will the repair take place? How will it be handled? Can you choose your preferred repair center?

If you let the insurer take full control of the repair without reviewing the terms, you might end up with a poorly repaired vehicle  and the struggle to demand compensation afterward can cost you both time and money.

Consulting a lawyer early ensures that you:

  • Understand your rights under your insurance policy
  • Know your options regarding repair types
  • Can take legal action if the insurer breaches its obligations

The Insurer’s Right Exists But It Must Be Fair

Ultimately, insurers do have the right to manage repairs, including using lump-sum arrangements.
However, that right must never override the customer’s right to fair treatment.
The car must be restored as closely as possible to its original state, not just “patched up” to save the insurer money.

If you’ve been in an accident, don’t wait until problems arise to seek legal advice.
Consult a lawyer immediately. It’s the best way to protect your rights and ensure a fair outcome.

WongSakorn Law Office

Our team of experienced insurance and compensation lawyers can help you file and pursue insurance claims properly and effectively ensuring you receive the full amount you deserve and that your car is restored to its original condition without compromise.

Let us “restore your rights” just like restoring your car  properly, and completely.

Car Accident Compensation: Why Filing with the OIC Might Not Work

Stay one step ahead of insurers—and protect your rights before it’s too late

When a road accident happens, many people assume that having insurance is enough. But in reality, claiming compensation—especially for “loss of use” of your vehicle—is not an easy matter. This often leads to lengthy disputes between the victim and the insurer. In many cases, even filing a complaint with the Office of Insurance Commission (OIC) may not yield results, especially if you lack legal knowledge or professional guidance.

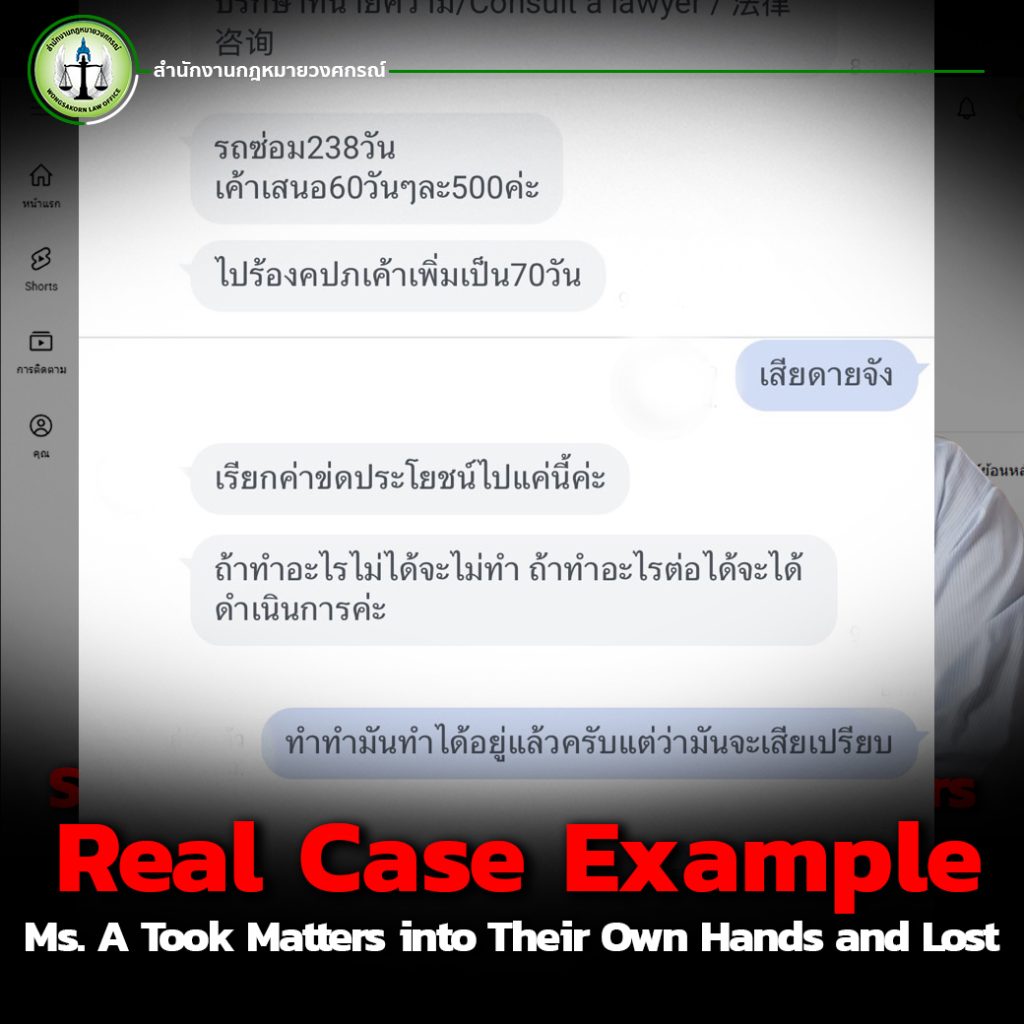
Real Case Example: Ms. A Took Matters into Their Own Hands—and Lost

In a clear example, Ms. A was involved in a car accident on July 10, 2024, and their car required 240 days of repairs. When they filed for “loss-of-use compensation,” the insurer offered only THB 500 per day for 60 days, totaling THB 30,000. Believing it was unfair, they filed a complaint with the OIC themselves. The OIC mediated, and the insurer increased the offer to 70 days—THB 35,000—still far below their actual loss.

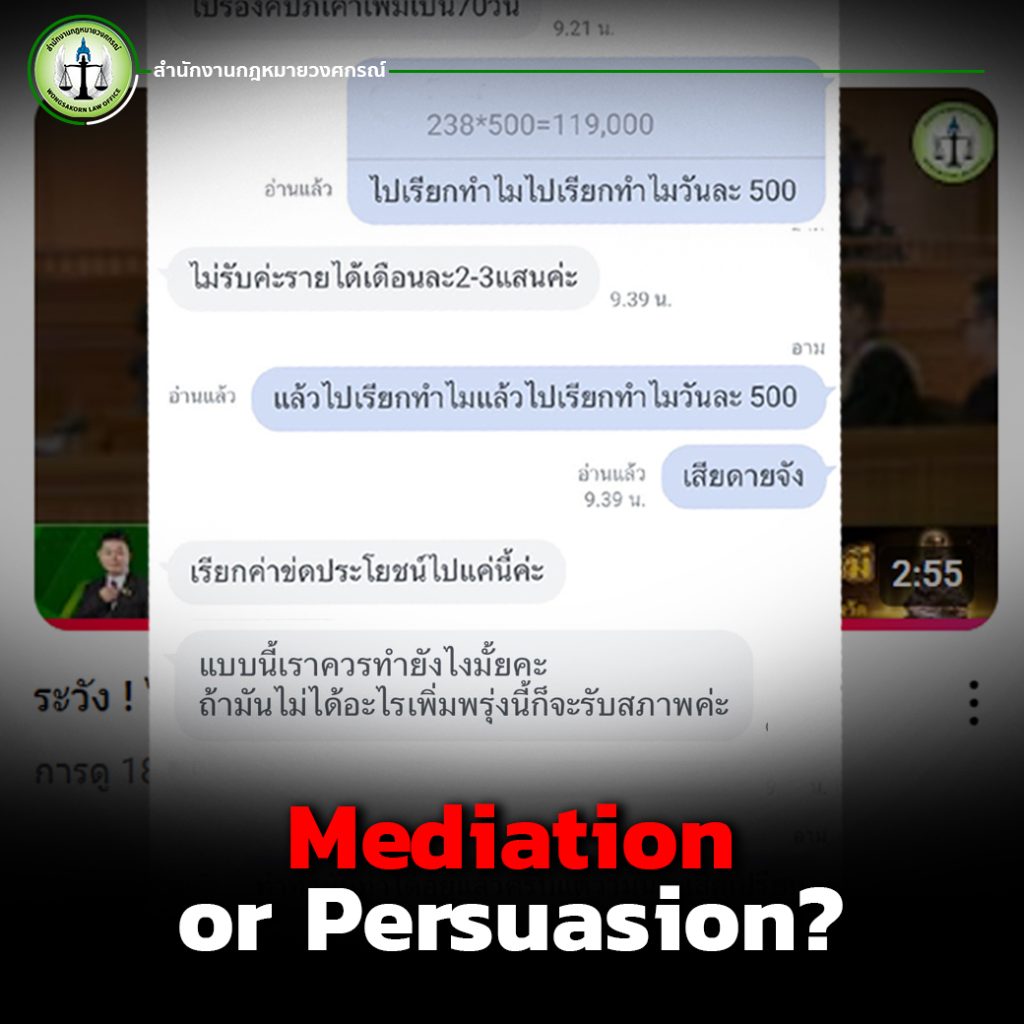
Mediation—or Persuasion?

Feeling unjustly treated, Mr./Ms. A then consulted Wongsakorn Law Office and spoke with Lawyer Arm, a specialist in insurance claims. But it was too late. Because the victim had initiated mediation before obtaining legal advice, they were at a disadvantage from the beginning.

Lawyer Arm explains:

“Mediation without knowledge often becomes persuasion—insurance companies come prepared with legal teams, negotiation tactics, even psychological strategies. If the victim lacks knowledge, they may agree to subpar deals, unknowingly giving up rights.”

Did You Know? You Can Claim More Than THB  500 Per Day!

Many believe “loss-of-use compensation” is capped at THB 300–500/day, but in truth, if you can prove actual financial loss—e.g., using the vehicle for business or delivery—you may claim THB 800–1,500 per day, depending on evidence and circumstances.

Key Point: Knowledge and Strategy Are Essential

Insurance companies often start with low offers. Without negotiation, proper documentation, or legal support, you risk losing deserving compensation.

Lawyer Arm’s Advice: Don’t Go to the OIC Alone if You’re Unsure

Many see the OIC as a last resort—which is true in theory. But in practice, if you go in without a plan or expert support, you might fall victim to what’s known as “rights-reducing mediation.” Insurers may use this stage to push you into accepting less, hoping to close the case quickly.

“If you intend to file with the OIC, hire a lawyer from the start—or at least seek legal advice beforehand.”
Once you’re at a disadvantage in OIC mediation, reversing or reclaiming your rights is extremely difficult, and you may lose them entirely.

Don’t Be Unnecessarily Disadvantaged!

🔍 Watch Lawyer Arm’s video tutorial series:

Key Takeaways

  • Don’t underestimate insurance companies—they have teams and tactics ready before any accident occurs.
  • You can claim more compensation than you may think.
  • Filing with the OIC without preparation may put you at legal disadvantage.
  • Consult an attorney from the start—that’s your best defense.
  • Don’t wait until you’ve lost your rights like Mr./Ms. A.

If you want to avoid going through a frustrating, unfair process, contact Wongsakorn Law Office today—or click “Contact Us” on their website.

Line @ คลิก! โทรหาเรา คลิก!